Newton: 316.283.6655
Andover: 316.202.9990

Newton: 316.283.6655
Andover: 316.202.9990
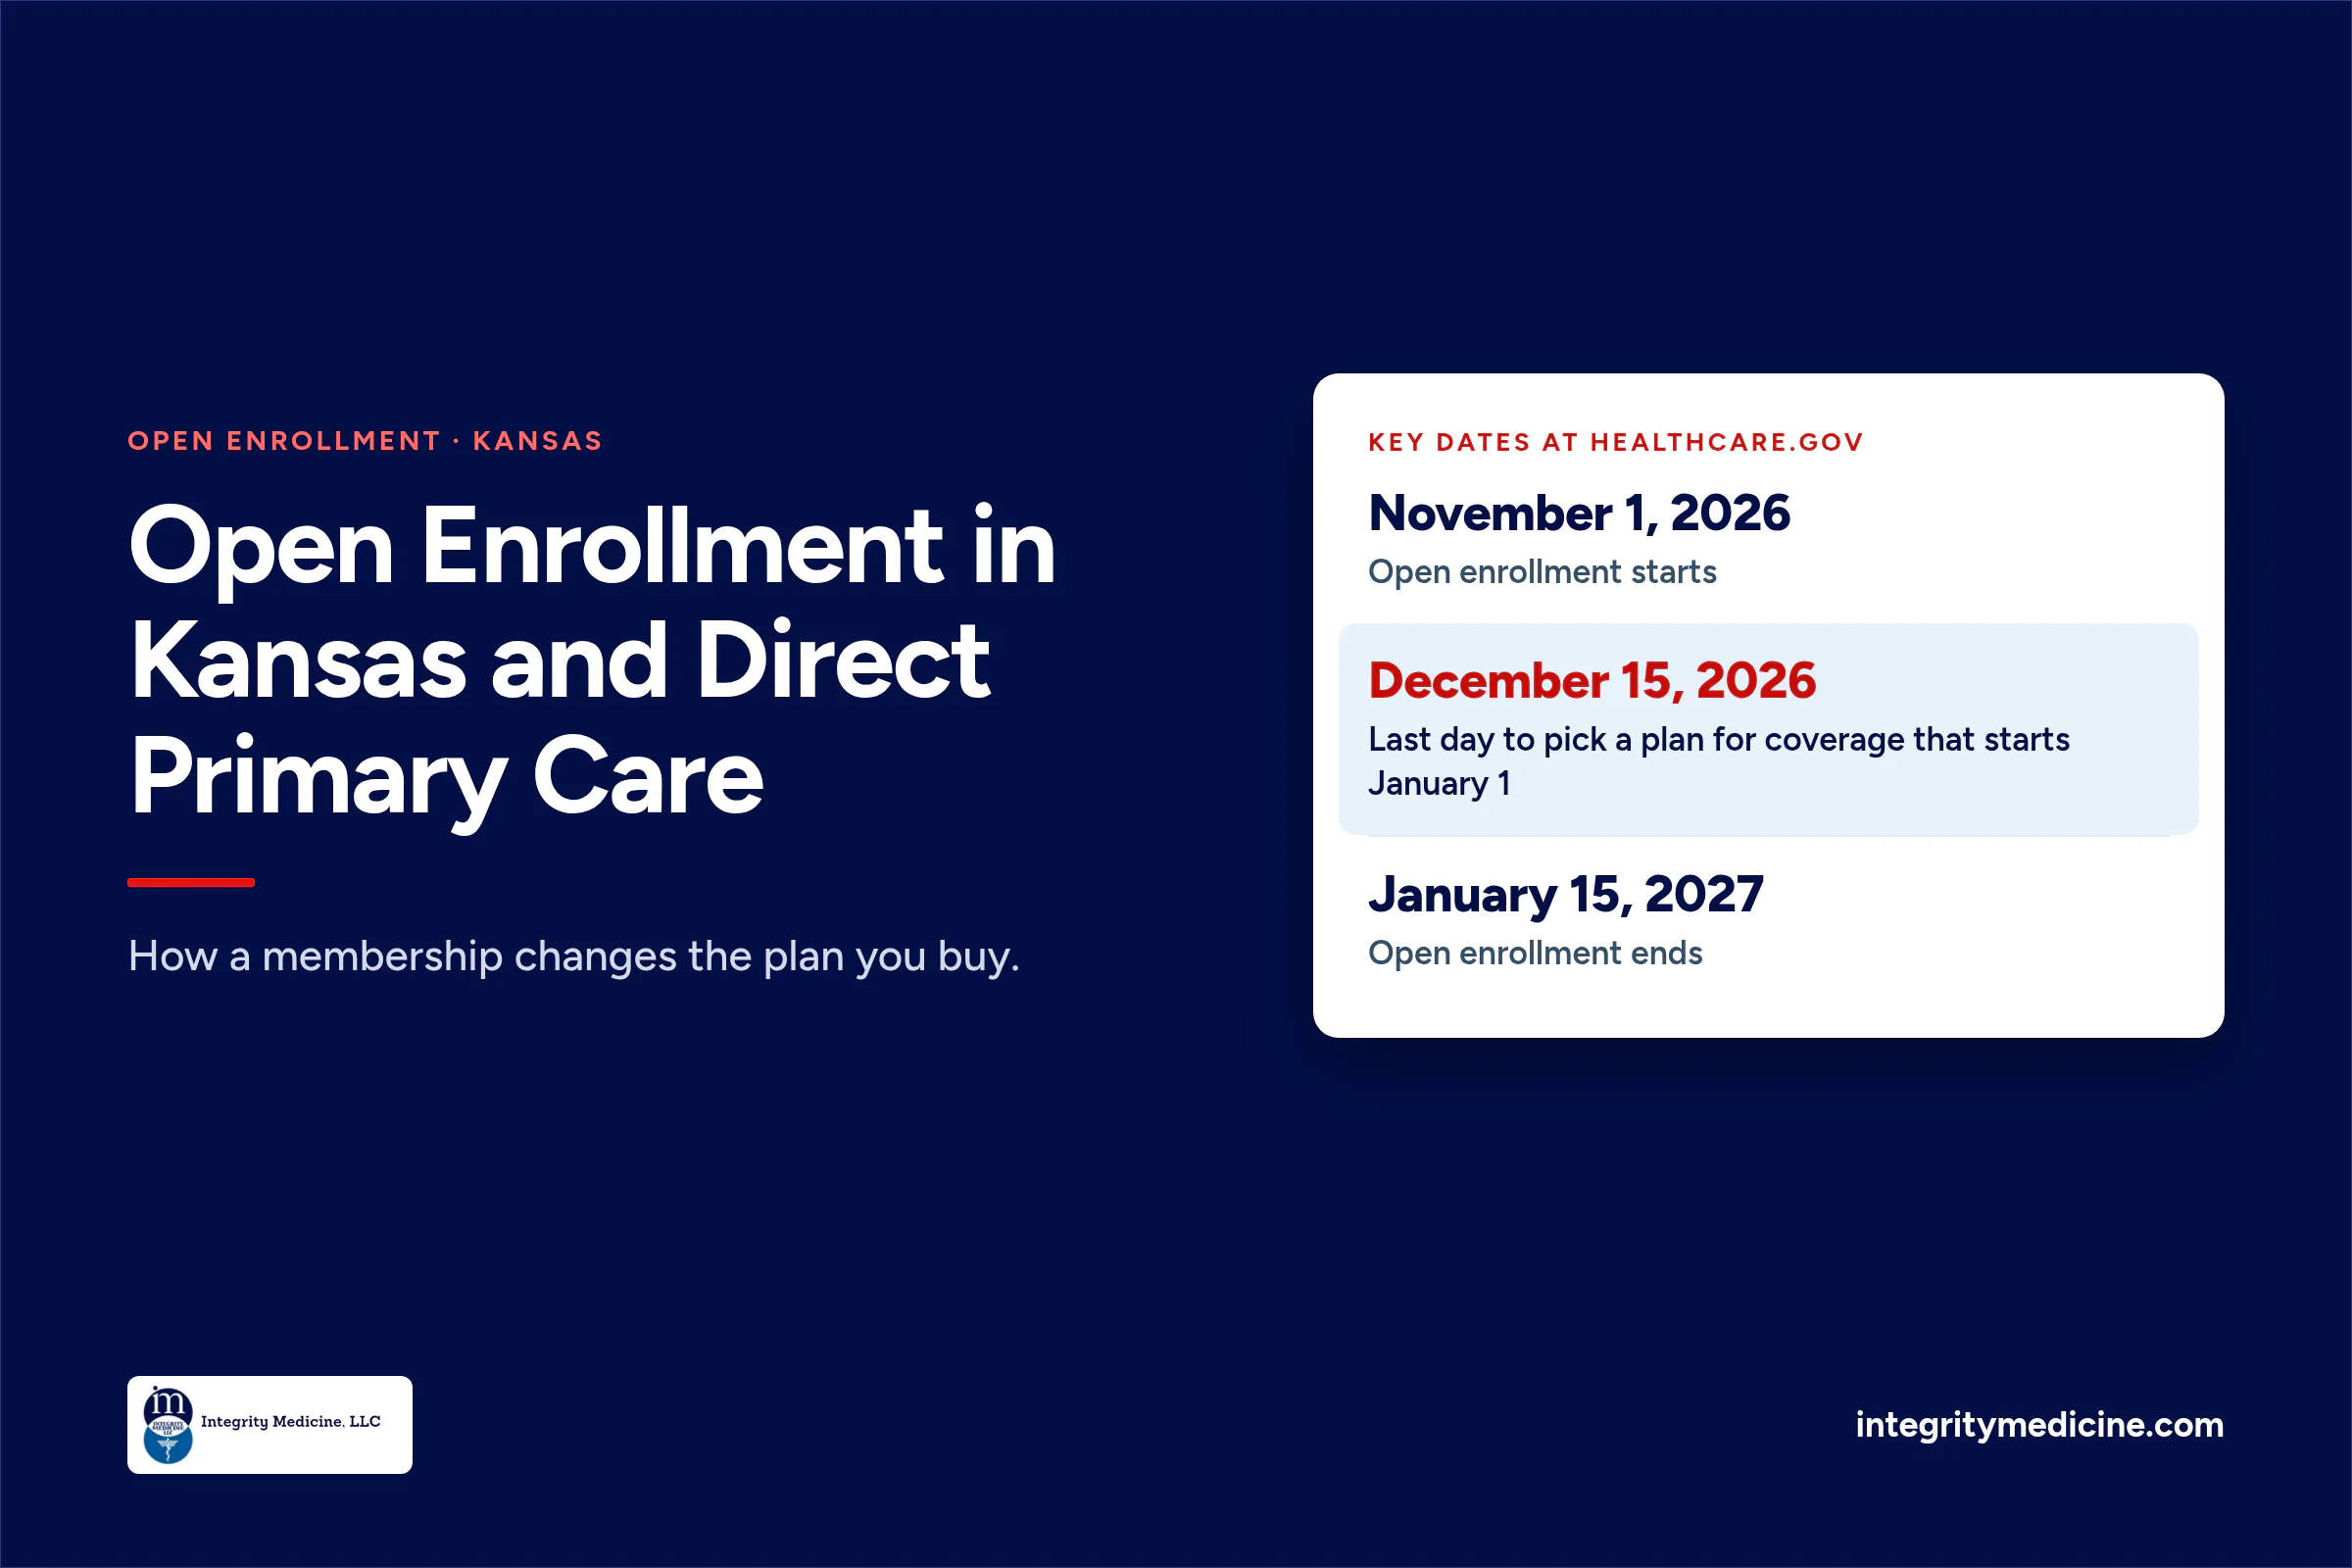
Health insurance open enrollment in Kansas runs November 1, 2026 through January 15, 2027, and you pick your 2027 plan at HealthCare.gov. Choose by December 15 and your coverage starts January 1.
If your family has a Direct Primary Care membership, or you're thinking about one, the plan that made sense last year may not be the best buy this year. Your everyday doctor visits are already handled. So the job your insurance has to do gets smaller, and that can change which plan you pick.
The 2027 dates, the HDHP vs PPO choice, the new HSA rules for bronze plans and a simple Andover family example are all worth a look before December 15.
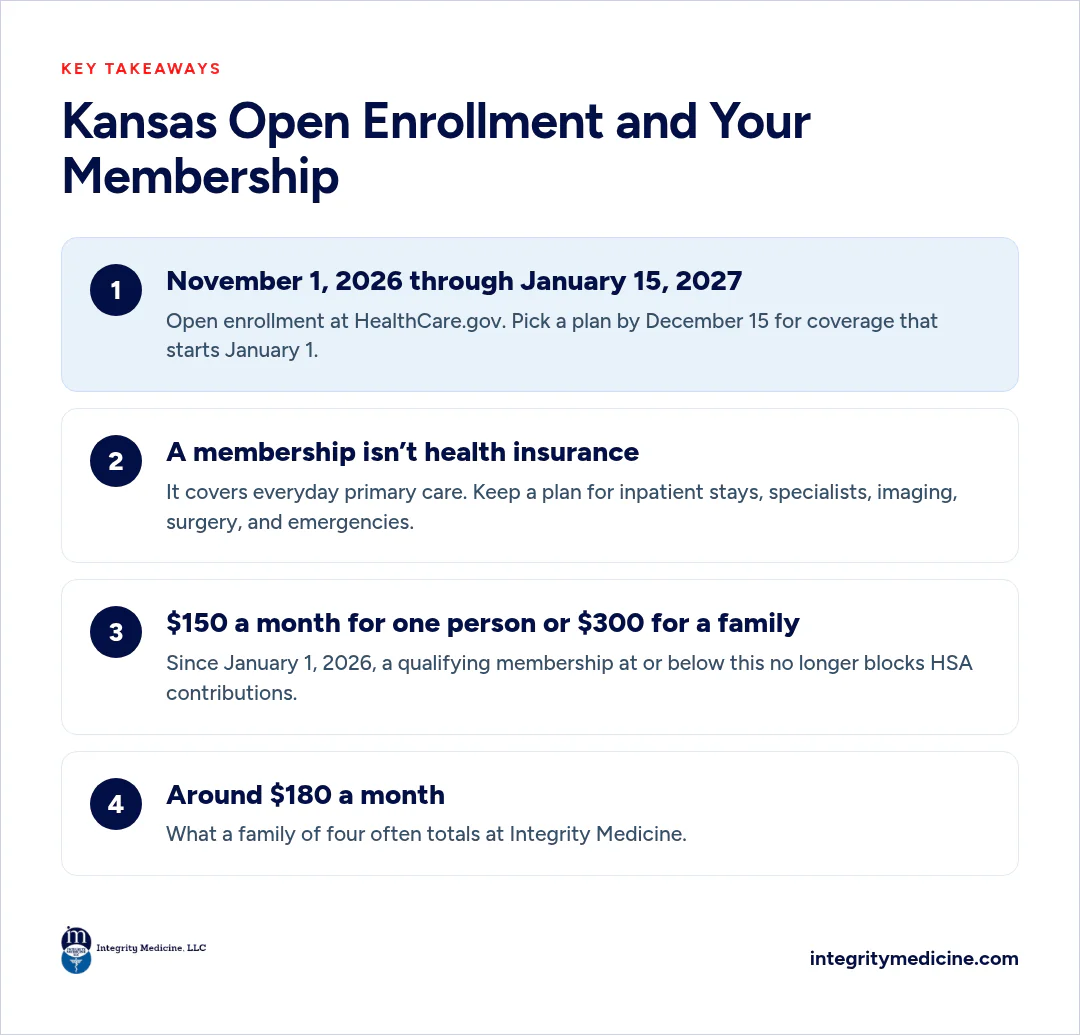
Kansans shop for 2027 individual and family plans at HealthCare.gov from November 1, 2026 through January 15, 2027. Pick a plan by December 15 for coverage that starts January 1; plans picked December 16 through January 15 start February 1.
| Date | What happens |
|---|---|
| November 1, 2026 | Open enrollment starts. You can enroll in, renew, or change a Marketplace plan for 2027. |
| December 15, 2026 | Last day to enroll or change plans for coverage that starts January 1. |
| January 1, 2027 | Coverage starts for plans picked by December 15, once the first premium is paid. |
| January 15, 2027 | Open enrollment ends. |
| February 1, 2027 | Coverage starts for plans picked December 16 through January 15. |
Source: HealthCare.gov dates and deadlines.
Kansas uses the federal Health Insurance Marketplace, so HealthCare.gov is where you compare plans, see your savings, and enroll. HealthCare.gov also lists free local help if you'd like someone to walk through plans with you.
After January 15, you can enroll or switch plans with a Special Enrollment Period, such as after a move, losing other coverage, marriage, or a new baby. KanCare (Medicaid) and CHIP accept applications any time of year. Source: HealthCare.gov Medicaid and CHIP.
If your coverage comes through work, your employer sets its own open enrollment window. The plan-choice ideas below work the same way for an employer plan.
Medicare has its own window. If you're 65 or older, our Medicare and Direct Primary Care page explains how a membership works alongside Medicare.

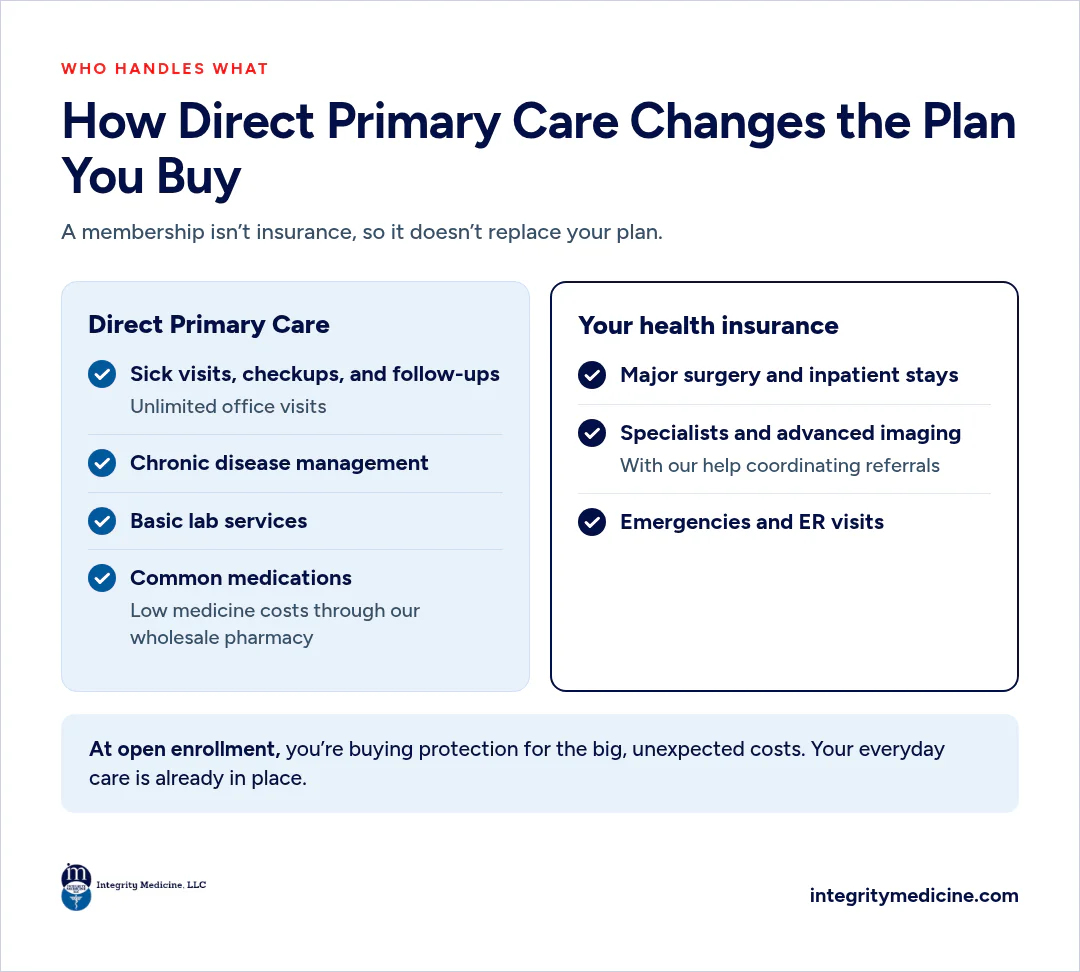
A Direct Primary Care membership covers your everyday primary care, so your insurance mainly needs to cover the bigger things: inpatient stays, specialists, imaging, surgery, and emergencies. That can make a lower-premium bronze or high-deductible plan, paired with an HSA, a better buy than a high-premium plan with low office copays.
Most people pick a plan by looking at the copay for a regular doctor visit. With a membership, that number matters a lot less, because unlimited office visits with your own doctor are part of the monthly fee.
| What you need care for | Who handles it with a DPC membership |
|---|---|
| Sick visits, checkups, and follow-ups | Direct Primary Care |
| Chronic disease management | Direct Primary Care |
| Basic lab services | Direct Primary Care |
| Common medications | Low medicine costs through our wholesale pharmacy |
| Major surgery and inpatient stays | Your health insurance |
| Specialists and advanced imaging | Your health insurance, with our help coordinating referrals |
| Emergencies and ER visits | Your health insurance |
Most of our members keep health insurance or a high-deductible plan for emergencies, inpatient stays, specialty care, and ER visits. A membership isn't insurance, so it doesn't replace that plan. Everyone should have some form of coverage for catastrophic events. What that looks like depends on your medical history and how much risk you're willing to take on. If you're weighing how a membership compares with a traditional insurance-based practice, we walk through it in our article on primary care with insurance vs Direct Primary Care.
When you need a specialist, our doctors coordinate the referral for you. You can see how that works on our specialist referrals and care coordination page.
At open enrollment, you're buying protection for the big, unexpected costs, and your everyday care is already in place. This is the unseen economics of membership: one incident that would otherwise have meant an urgent care or ER visit can potentially cover a year of membership on its own.
If your membership handles routine visits, one of a PPO's selling points, low copays for office visits, matters less, and a high-deductible plan's lower premium and HSA eligibility matter more. A PPO can still be the better fit if you expect surgery, a pregnancy, or frequent specialist care next year.
| A high-deductible plan with an HSA may fit if | A PPO may fit if |
|---|---|
| Your membership covers most of the care you use in a typical year | You expect a planned surgery or an inpatient stay |
| You'd rather pay a lower monthly premium | You're expecting a baby next year |
| You want to save pre-tax money in an HSA | You see one or more specialists often |
| Your family is generally healthy | You'd prefer set copays for specialist visits |
For 2027, the IRS defines a high-deductible health plan as one with a deductible of at least $1,750 for self-only coverage or $3,500 for family coverage, and out-of-pocket costs capped at $8,700 or $17,400. Source: IRS Rev. Proc. 2026-24.
A plan's out-of-pocket maximum is the most you'd pay for covered care in a year. With a membership covering everyday visits, that number is the one to compare side by side. Membership fees don't count toward a plan's deductible or out-of-pocket maximum.
Our guide to what covered really costs covers the math of premiums plus deductibles and the timing rules that can surprise people.
Since January 1, 2026, bronze and catastrophic plans count as HSA-compatible high-deductible plans, even when they don't meet the usual deductible numbers. That covers plans you buy on HealthCare.gov, and the same plan bought straight from an insurer as long as it's also offered on the Marketplace. Source: IRS Notice 2026-5.
That makes a bronze plan worth a fresh look for a family with a membership. A bronze plan with an HSA can cover the large costs while your membership handles everyday care. One catch: catastrophic plans never qualify for the premium tax credit, so compare full premiums.
A silver plan can still be the better choice for some households. If you qualify for extra savings on deductibles and copays, HealthCare.gov applies them only to silver plans, so compare both side by side before December 15. Source: HealthCare.gov extra savings.

Since January 1, 2026, a qualifying Direct Primary Care membership no longer stops you from contributing to an HSA, as long as its fees stay at or below $150 a month for one person or $300 a month for a membership that covers more than one person. You can also pay a qualifying membership from your HSA. Those limits stay the same for 2027. Sources: IRS Notice 2026-5; IRS Rev. Proc. 2026-24.
For 2027, you can contribute up to $4,500 to an HSA with self-only coverage or $9,000 with family coverage. Source: IRS Rev. Proc. 2026-24.
Every Integrity Medicine membership tier stays under the $150 individual limit. Confirm how this fits your plan and taxes with your accountant or HSA administrator. We cover the details in using your HSA for the membership.

The premium tax credit lowers your monthly Marketplace premium, and HealthCare.gov estimates it when you apply. Households with income from 100 to 400 percent of the federal poverty line can generally qualify. If your income ends up higher than estimated, you now repay any extra advance credit in full at tax time, since repayment caps ended after 2025, so keep your application current. Source: IRS premium tax credit questions and answers.
The wider eligibility Congress allowed for 2021 through 2025 has ended, so your savings for 2027 may look different from what you remember. Preview your estimate on HealthCare.gov before you compare plans.

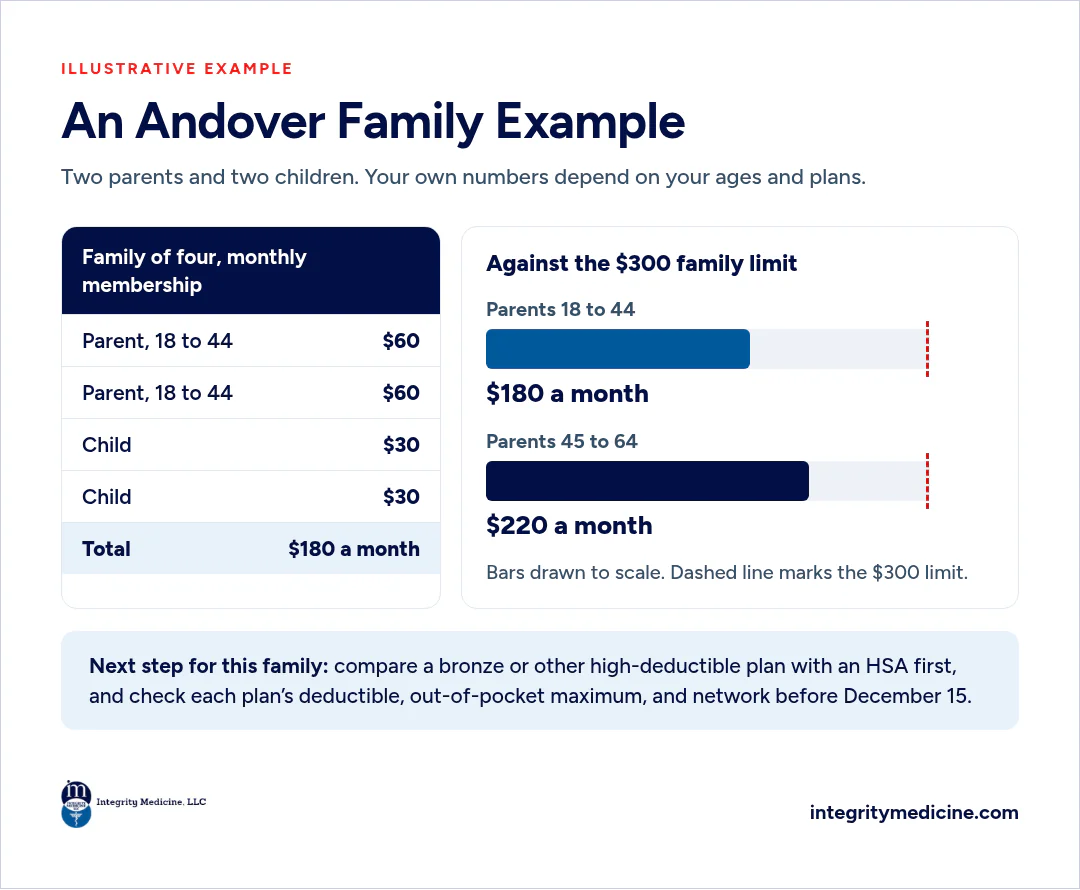
Picture a family of four in Andover with two parents under 45 and two children. This example is illustrative, so your own numbers will depend on your ages and the plans offered to you.
Their membership at Integrity Medicine looks like this, using our membership prices:
| Family member | Monthly membership |
|---|---|
| Parent, 18 to 44 | $60 |
| Parent, 18 to 44 | $60 |
| Child | $30 |
| Child | $30 |
| Total | $180 a month |
A family of four often totals around $180 a month, which sits under the $300 family limit for keeping HSA contributions. If both parents are 45 to 64, the total is $220 a month, still under that limit.
With everyday visits, checkups, and basic labs handled by the membership, this family can shop open enrollment for the plan that best covers surgery, specialist care, or an ER visit. For many families in that spot, a bronze plan or another high-deductible plan with an HSA is worth comparing first.
They'd still check each plan's deductible, out-of-pocket maximum, and network on HealthCare.gov before December 15.
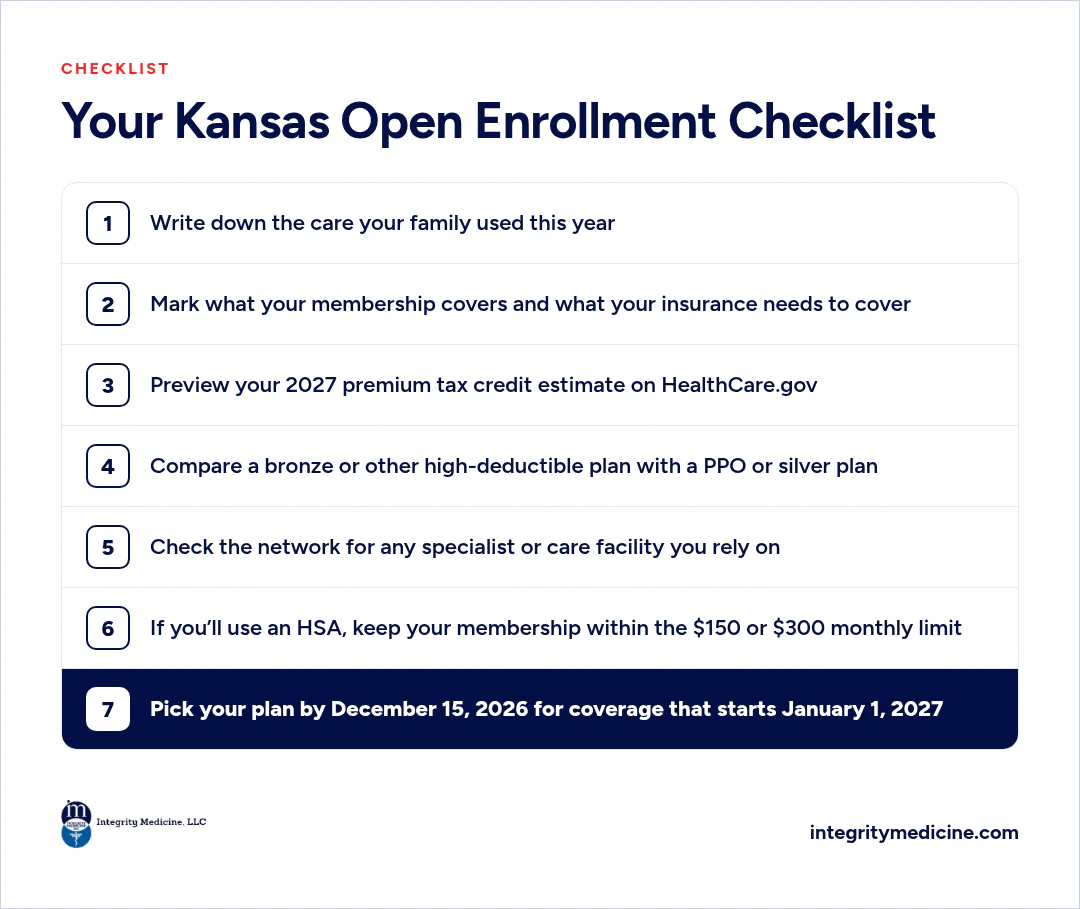
Health insurance open enrollment in Kansas runs November 1, 2026 through January 15, 2027 at HealthCare.gov. Pick a plan by December 15 for coverage starting January 1, or by January 15 for coverage starting February 1.
A high-deductible plan is often worth a close look when a Direct Primary Care membership already covers your everyday visits, because you trade low office copays you won't use for a lower premium and HSA eligibility. If you expect surgery, a pregnancy, or frequent specialist care next year, compare a PPO's total costs too.
You can, and it's one of the friendliest changes for families like yours. Since January 1, 2026, bronze and catastrophic plans offered on the Marketplace count as HSA-compatible, and a qualifying membership up to $150 a month for one person or $300 for a family doesn't block HSA contributions. You can also pay the membership from your HSA.
After January 15, you can enroll in or change a Marketplace plan with a Special Enrollment Period, such as after a move, losing other coverage, marriage, or a new baby. KanCare (Medicaid) and CHIP accept applications any time of year.
Employer open enrollment follows the window your employer sets, and the same thinking applies: with a membership covering everyday care, compare plans on premium, deductible, out-of-pocket maximum, and HSA eligibility. Your HR team can confirm whether a high-deductible option qualifies for an HSA.
Open enrollment goes more smoothly when your everyday care is already settled. Our Andover clinic is at 338 S. Andover Road, Suite 200, serving families from Andover, east Wichita, and the rest of Butler County. Learn more about Direct Primary Care in Andover.
Dr. Anna Cleland-Leighton is a board-certified Family Medicine physician who lives in Andover with her family and is accepting new patients.
We'd love to meet you before you pick your plan. Your meet-and-greet with the doctor is free, so you can decide we're the right fit before you sign anything. Contact us or call 316.202.9990.